 Keep My Acres
 The short version
- Effective January 1, 2026. Passed 145–0 in the House and 31–0 in the Senate.
- Some sales no longer count as an ownership change for ag, wildlife or timber valuation (Tax Code §23.54(e-1)).
- Those owners get a longer, penalty-free window to file their application (§23.541(a-2)).
- Everything else stays the same: the April 30 deadline, the 5-of-7-year history, the 3-year rollback, the wildlife rules.
 Before 2026
When ag land changed hands, the new owner had to file a new application by April 30. The only exception: land passing to the owner's surviving spouse. Miss April 30 and you paid a late penalty, or lost the valuation for the year.
 What changed
A sale still counts as no ownership change in two cases:
- Surviving spouse. Same as before.
- Same use, same people. New: after the sale, you use the land in materially the same way the old owner did the year before, and that use is overseen or run by the same people who ran it the year before.
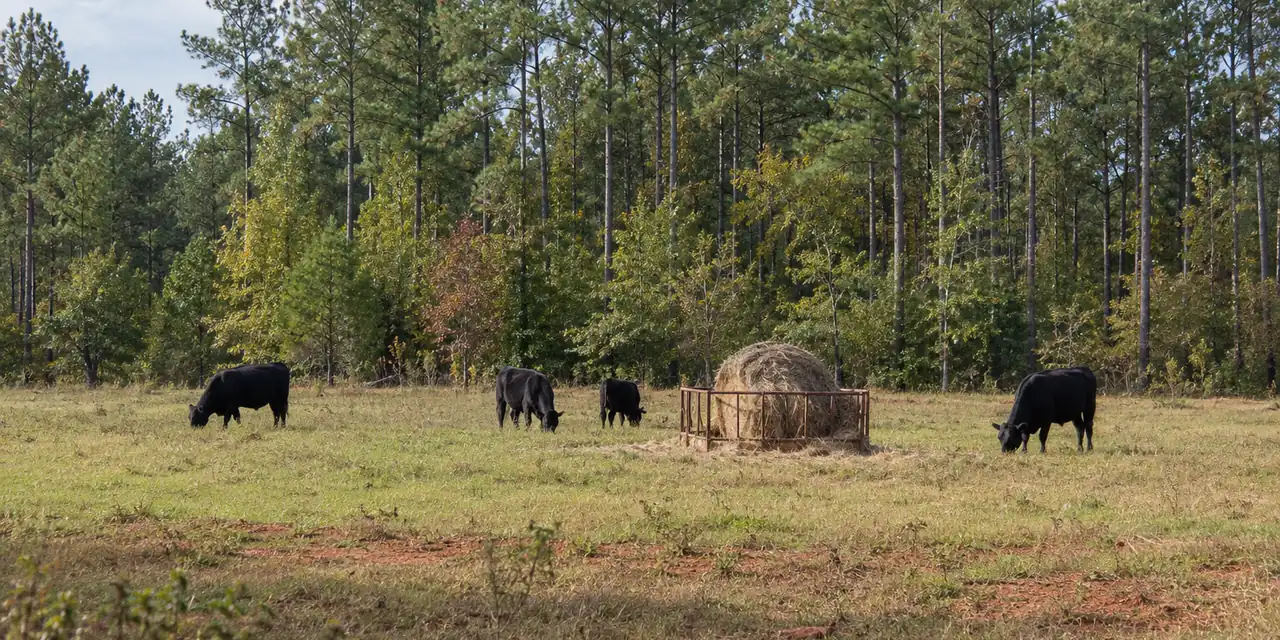
Example that fits: You buy 40 acres in Polk County. The neighbor who ran cattle on it for the old owner keeps the same lease and the same herd. Same use, same person.
Example that doesn't fit: You buy the same 40 acres, the old lease ends, and you bring in your own cattle or switch to hay. The use or the people changed. File by April 30 like before.
 The new filing window
If you fit the same-use, same-people rule, the appraisal district must still accept your application after April 30, as long as you file by the later of:
- the date the taxes on the land become delinquent for that year (usually February 1 of the next year), or
- one year after you took ownership.
Example only. You get whichever is later: the delinquency date or one year after closing (§23.541(a-2)). Taxes usually go delinquent February 1.
The usual 10% late penalty doesn't apply to these filings (§23.541(b)).
 Who decides if you fit
Your appraisal district. "Materially the same way" isn't defined in the bill, so the chief appraiser makes the call on your facts. Paperwork that helps: the lease, the lessee's name, and records showing the same cattle, hay or timber work the year before and after.
Our advice: don't count on the exception if you don't need it. If you can file by April 30, do. The exception is a safety net, not a plan.
 What didn't change
- The deadline. April 30 is still the normal deadline.
- History. Land still needs ag use in 5 of the last 7 years (§23.51).
- Rollback. Still the tax difference for the 3 years before a change of use (§23.55). Rollback guide and calculator.
- Wildlife. Still 3 of 7 activities under Texas Parks and Wildlife's guidelines. Switching to wildlife.
Other 2025 bills would have changed the history rule, small farms and exotic animals. None of them passed.
 What to do if you just bought land
- Find out who ran the land last year and whether they're staying on.
- Get the lease or a short written statement from them.
- File Form 50-129 with your county's appraisal district. Before April 30 if you can.
Full new-owner guide · We'll prepare your application for $69
Your county
Each county's appraisal district decides whether your use is "materially the same":
General information, not legal or tax advice. Your appraisal district makes the final call.